
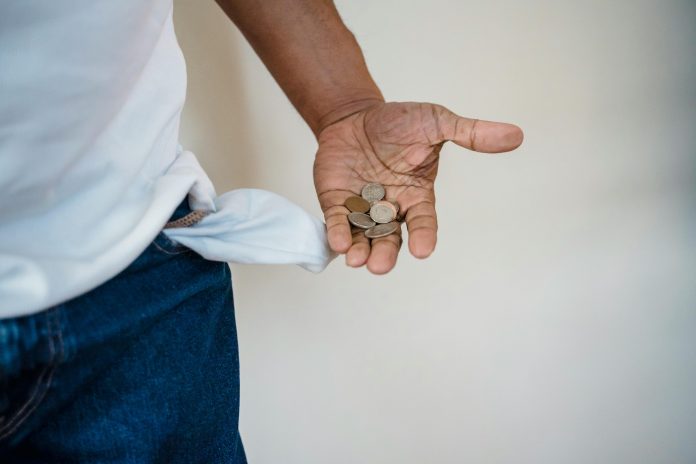
New Standard Bank analyses revealed that nearly half of salary earners are left with less than R1,000 or have negative balances by payday.
Data from over 400,000 individuals, who receive their salaries on popular payment dates, including mid-month, the 25th, and month-end, shows the day before payday, 21% had R1,000 or less, while 28% had negative balances or were using overdrafts. Only half had more than R1,000 in their accounts.
Emerging middle-income earners had the highest percentage of customers with less than R1,000 or in the red, but private banking customers aren’t exempt either, with one in ten customers having a negative balance before payday.
The Head of Personal & Private Banking at Standard Bank South Africa, Kabelo Makeke, says while this insight might be discouraging, there are effective strategies to help manage your finances better.
“This situation highlights the growing challenge of balancing income with lifestyle in today’s fast-paced world. However, it also presents an opportunity for individuals to take proactive steps toward financial resilience.”
Makeke adds that this trend may also be influenced by the increasing availability of overdraft facilities.
“Many customers hold accounts with multiple banks, which can lead to misinterpretations of their financial health. They may be transferring funds to savings accounts elsewhere closer to payday, demonstrating a potential for better financial management.”
However, Makeke says that where customers are living with no real financial cushioning because they spend large portions of monthly income early in the month leaving little to cover unexpected expenses, closing the salary-lifestyle gap is crucial.
“The challenge of balancing income with lifestyle appears to increase as earnings rise, with more individuals falling into the trap of lifestyle inflation.”
Although high-income earners often enjoy greater disposable income, Standard Bank’s findings show they are also more susceptible to negative balances, raising awareness about lifestyle inflation, a phenomenon where rising incomes lead to higher spending that often outpaces earnings.
“As incomes rise, it’s easy to fall into the trap of spending more, which can create a cycle of debt. However, breaking this cycle is possible.”
Makeke shares some tips:
- Make small, consistent changes, such as tracking expenses
- Create a budget aligned with future goals
- Pay off high-interest debt
- Prioritise having emergency savings to reduce reliance on credit, making it easier to manage unexpected expenses